Unpaid labour: more than a salary allocation

Principles in Practice

Unpaid labour: more than a salary allocation

Unpaid labour often takes a minute to fully understand. I’ll run through what it is again in this article, however I also want to add in a few hidden implications of not understanding unpaid labour.

What counts as unpaid labour?

Technically, unpaid labour is a non-cash representation of the true labour costs required to run your business. We calculate this by asking how many weeks of work were done by someone who meets the following two criteria:

  1. They were not being paid a fair market wage, AND
  2. If they didn’t do the work, then you would have had to pay someone else to come in and help get the work done.


It is important to consider how many weeks of work you’d actually need if a contractor came in. For example, if you’ve got three kids out mustering for two weeks during the holidays, would you have had to employ three contractors for two weeks if the kids weren’t there? If the answer is yes, then six weeks unpaid labour is appropriate. In reality if you could have got the job done with just one kid (or one skilled person) then the correct allocation would two weeks.

What is a fair market wage?

At a minimum it needs to be award rates with inclusions. The other test is to ask if someone else would come and do the same work for that pay? I often see businesses not including some people in unpaid labour allocation because they are being paid a wage, rather than drawings. But is it a market value wage?

Unpaid labour generally applies to family members, however it can apply to anyone who meets the above criteria such as friends or volunteers.

We then allocate a value to the number of weeks of work done.

Why go to the effort?

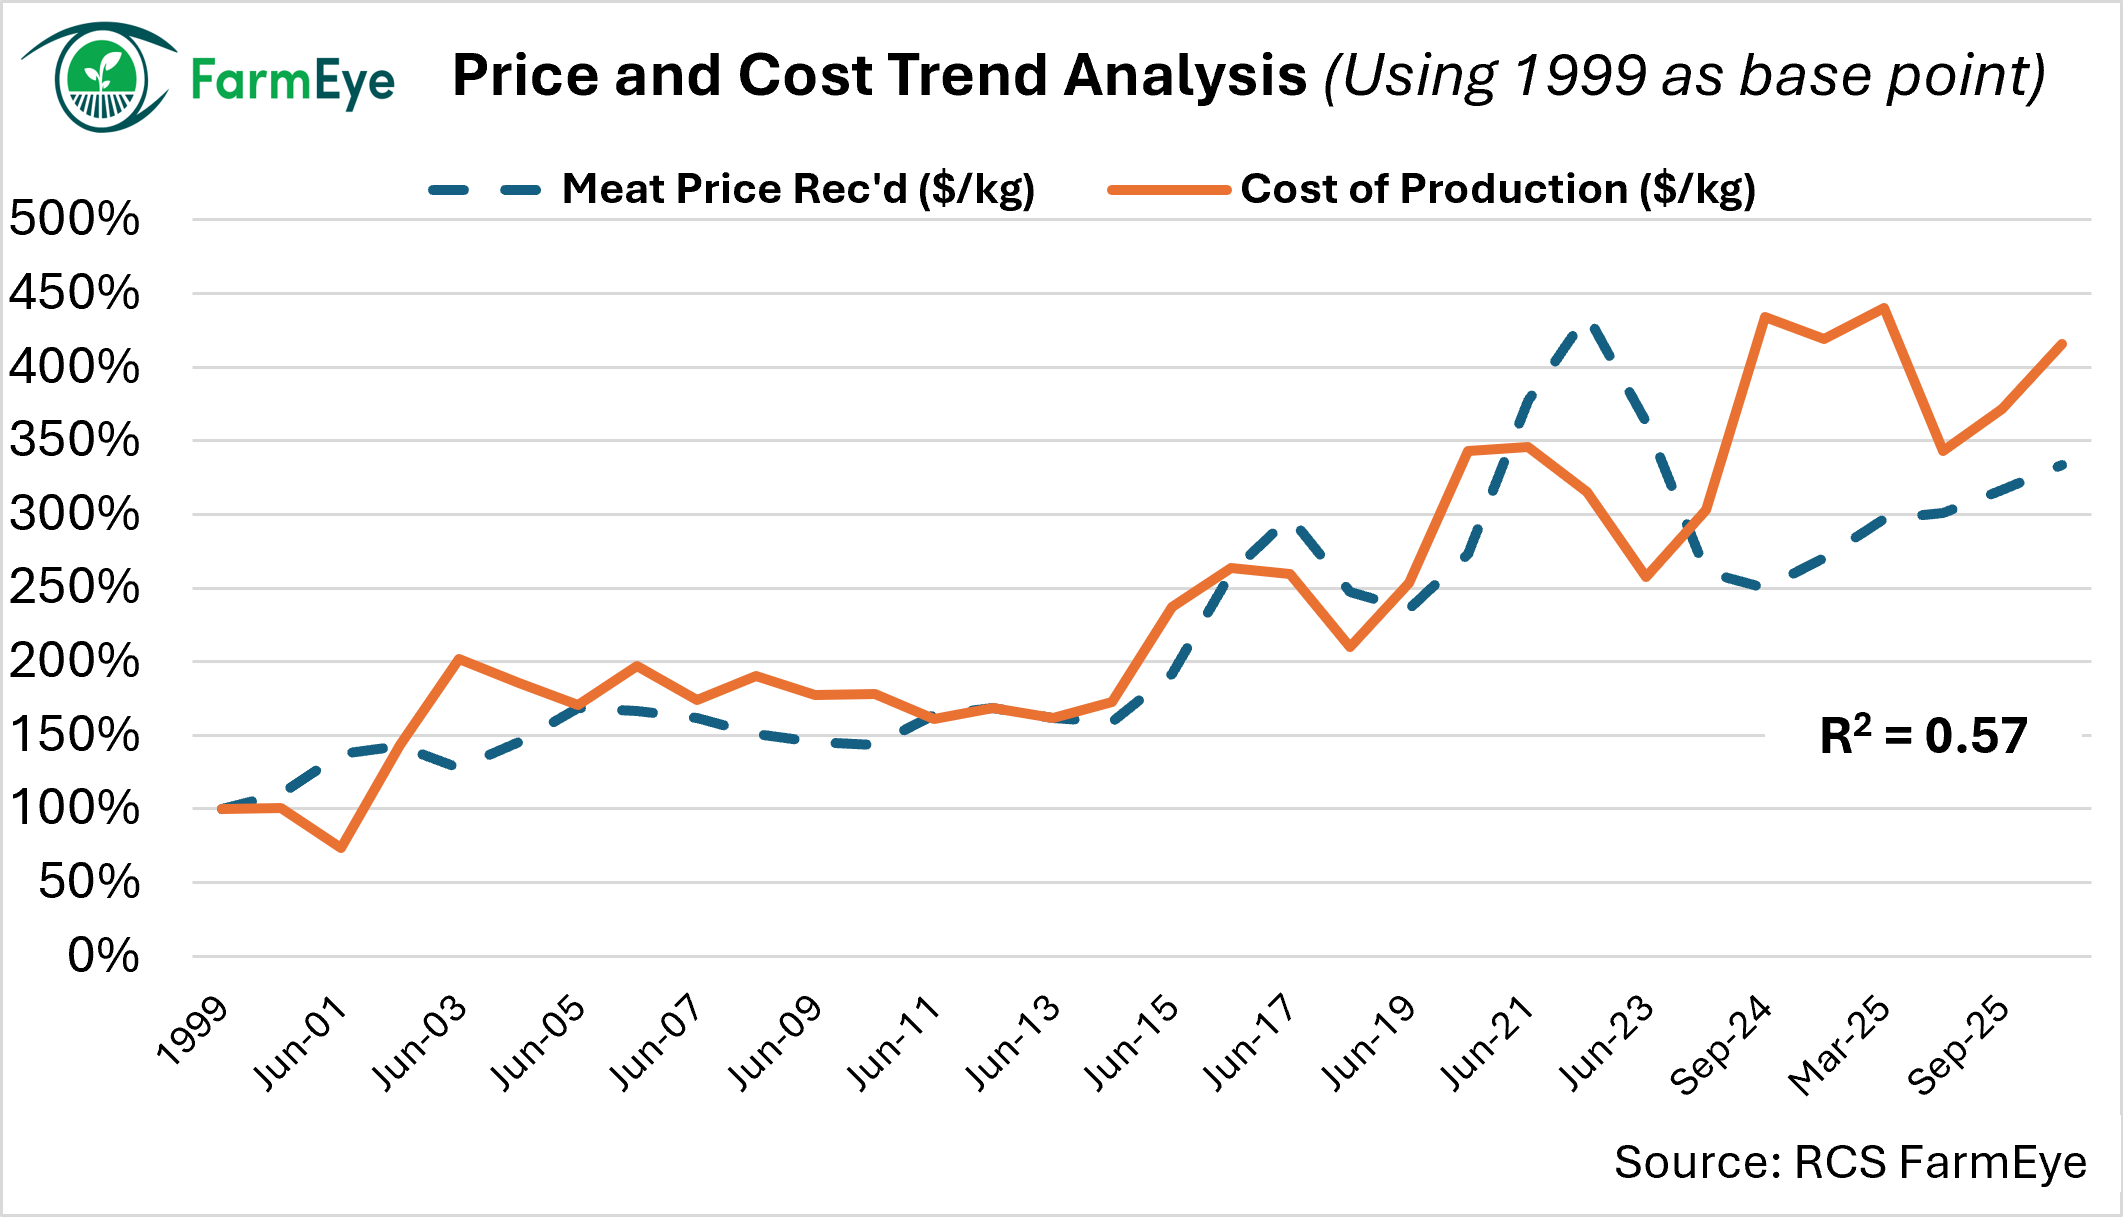
If you want to calculate the real profitability of your business, and you aren’t including unpaid labour, then you are subsidising the business.

Unknown

Where do drawings fit in?

Drawings (like under market value wages) are a CASH consideration. They are the physical amount of cash you require. This is usually different to the market cost of labour, what you’d need to pay someone else to do that work.

Think about drawings at different stages of life.

When you are in the early stages of a business for example, young couple, no kids, setup phase you quite literally can live off the smell of an oily rag. You take only enough drawings to support the minimum lifestyle as you choose to utilise cash for capital expenditure and setting up the business.

Now what about a business who has three kids at boarding school! Unfortunately, the smell of an oily rag does not cover boarding school fees. The amount they need to pull out in drawings above their living costs could be five to ten times higher.

Drawings are a cash flow consideration, however cashflow does not indicate business profit. Use drawings for calculating cashflow and replace them with unpaid labour when calculating economic profit.

Why does this matter for the future of the business?

I’ve seen more than one occasion where a client hasn’t wanted to include unpaid labour because it has shown them as making an economic loss. The first question to ask is whether the result is repeatable, or whether it is because you’re in the setup phase with high overheads and low turnover?

If you’re not in setup phase and the business can’t pay the true cost of labour, this is a red flag for business continuity and succession. If the business can’t fund the true cost of labour now, then how will you fund the next generation coming into the business, and your living costs and lifestyle as you transition out. How will succession work if the business cannot afford the true labour cost required to operate it? I haven’t got any data to back this up, however my feeling is that there is a strong correlation between a business that can’t afford to pay the real cost of labour and the need to sell a land asset or external asset to fund succession.

What do you do with this information? My suggestions are:

  1. Know the economic profit of your business. FarmEye and the RCS templates can help you do this – contact your RCS Advisor for support or email advisory@rcsaustralia.com.au
  2. If you’re not generating an economic profit, then determine what changes to your business are needed to create sufficient profit to meet your goals.


Putting your head in the sand isn’t a great strategy. The earlier you know your position and start taking action, the easier it will be to move forward.

Or, you may need to start planning for sale of an asset at some point in the future.

RCS Logo

Join our mailing list